Bodily Injury Exclusions in Tech E&O and When AI Crosses Into GL Territory
Physical AI systems fall between Tech E&O and General Liability coverage gaps.
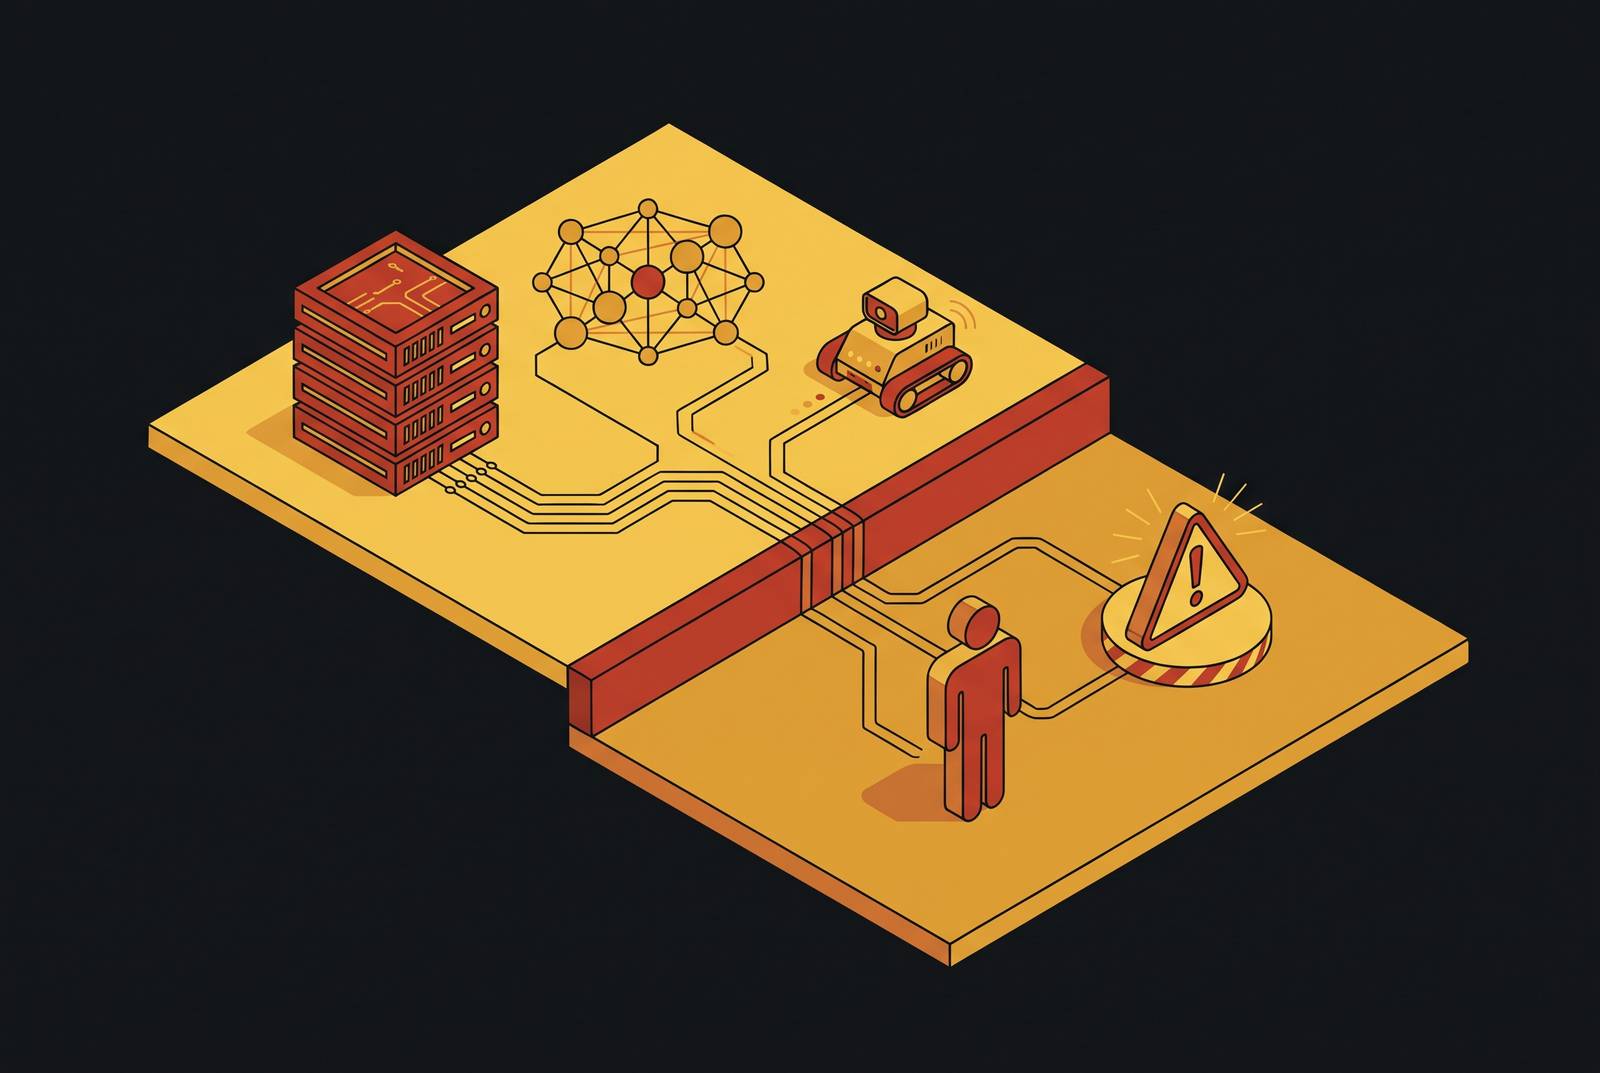
Physical AI exposes a gap between Tech E&O, which typically excludes bodily injury, and General Liability, which increasingly excludes AI-related losses. Closing that gap requires more than an affirmative AI label. A company must match the harm its system can cause to the actual coverage trigger, then document the governance that makes that risk insurable.
Why AI bodily injury claims fall between Tech E&O and General Liability
Tech E&O and Commercial General Liability divide risk by categories that do not align neatly when software controls a machine. Tech E&O covers financial loss when technology fails, including when outputs are wrong or services fail to perform. CGL addresses physical harm to third parties, such as injury from a falling shelf or defective machine part. The cause looks like a technology failure, while the resulting bodily injury or property damage belongs in the liability coverage built for physical harm.
Moffatt v. Air Canada, 2024 BCCRT 149 illustrates the professional-liability shape of an AI output claim through financial reliance on a chatbot’s wrong answer. A delivery robot striking a pedestrian presents a different loss. CGL grew out of coverage for human operators and incidents caused by people, while Tech E&O was built to cover professional liability and leaves out bodily injury. Putting both policies in a program does not, by itself, connect their coverage across that boundary.
How "silent AI" coverage was removed from both policies starting January 2026
Before 2026, existing policies could respond to AI losses without expressly naming AI, a pattern called “silent AI,” following the earlier pattern of silent cyber. Where wording neither covered nor excluded the technology, a flawed report produced by a language model could receive the same treatment as one produced by a junior analyst. Silence could benefit the policyholder, subject to the policy’s other terms. Starting January 1, 2026, standardized exclusions and carrier-specific changes began replacing that default with express restrictions on both sides of the program.
ISO introduced three optional CGL endorsements effective January 2026. CG 40 47 removes Coverage A, for bodily injury and property damage, and Coverage B, for personal and advertising injury, arising from generative AI. CG 40 48 removes only Coverage B, for claims that include defamation, copyright infringement, and invasion of privacy from AI-generated content. CG 35 08 addresses bodily injury and property damage arising out of generative AI under products and completed operations coverage. Adoption is not automatic across the market. The forms instead give carriers regulator-reviewed exclusion language that can produce different coverage for companies renewing in the same month.
Berkshire Hathaway, Chubb, and Travelers moved in early 2026 to remove AI liability from standard commercial policies. Tech E&O has no equivalent ISO exclusion framework yet, but some carriers have broadened software and professional-services exclusions to reach claims arising from AI, machine learning, or model output. At renewal, previously silent coverage may be expressly allocated or deleted, often without a corresponding premium reduction. Risks that underwriters cannot price are being excluded.
Where CG 35 08 specifically targets companies deploying AI in hardware
CG 35 08 extends these exclusions to products and completed operations that involve generative AI. Its significance for physical deployment is not a side effect of disputes about generated text. The risks it targets include those from autonomous systems, robotics, and AI-directed physical operations. Delivery drones, warehouse automation, sidewalk robots, and autonomous vehicle fleets all need protection for bodily injury and property damage. The wording’s generative AI scope remains important when determining whether a particular system’s loss falls within it.
Physical autonomy also changes the cost of failure. Taking human error out can lead to fewer incidents but make each one that does occur cost more. A collision may require sensor recalibration, radar replacement, and software-stack revalidation in addition to a bumper repair. Fewer incidents do not necessarily make the remaining losses straightforward to insure.
Meeting technical rules does not ensure that a company can get insurance either. Delivery robots on sidewalks, cleaning robots in airports, shelf-scanning robots in grocery stores, and hospital service robots operate around unpredictable, untrained people. Insurance tolerance for that combination can be lower than public or technical tolerance. Underwriters also lack the familiar demographic proxies used for human operators, including age, distraction history, and fatigue. In that setting, the exclusion functions as a placeholder for a pricing framework that has not yet been established.
Why Tech E&O doesn't catch what CGL now drops for physical AI claims
The natural fallback fails because Tech E&O classifies the loss differently from the technology that caused it. An allegation of algorithmic error does not turn a pedestrian’s injury into covered professional-liability financial loss. Bodily injury exclusions remain an independent barrier. Where CG 35 08 removes the relevant physical claim from CGL, a standard Tech E&O policy does not acquire responsibility simply because software was involved.
Some carriers extend legacy exclusions to AI, machine learning, or automated decisioning, while standard forms can also exclude claims arising from custom-built models. Companies training or fine-tuning systems for physical deployment therefore need to account for both the harm and the model’s treatment under the wording. Contract terms add another potential gap. An AI vendor’s indemnification clause can create obligations for the deploying company that encounter contractual-liability exclusions in both CGL and Tech E&O.
W. R. Berkley’s absolute exclusion illustrates how far the restriction can extend, reaching D&O as well as operational liability. Where the applicable CGL endorsement excludes the event and Tech E&O excludes the resulting harm, neither policy supplies the missing coverage. This is a genuine uninsured exposure under those terms.
What the full coverage stack actually looks like for a company deploying AI in the physical world
Tech E&O or Professional Liability addresses financial loss from output errors, model failures, and failure to perform as contracted, with affirmative AI wording. CGL addresses premises bodily injury, property damage, and contractual additional-insured requirements. However, renewals adopting CG 40 47 or CG 35 08 remove the AI-related losses within those endorsements’ respective scopes.
Cyber addresses data breach, ransomware, and AI used as an attack vector. Some affirmative endorsements expand a security failure to include AI security events, but that does not make cyber a general policy for model outputs or physical harm. D&O serves a different layer of liability. It concerns management decisions, including an AI governance failure that harms shareholders, and therefore needs its own review for exclusions such as Berkley’s.
Inland Marine or Equipment coverage addresses physical hardware, robotics, sensor arrays, and custom equipment in transit or at customer sites. It becomes important when a high-value lidar-equipped platform leaves the premises that standard property coverage follows. Product Liability addresses another distinct exposure. Where an AI system includes hardware or controls a physical process, bodily injury and property damage from that deployment are product-liability claims in substance. Coverage must be written for that exposure explicitly.
Affirmative AI coverage products that now exist to fill the gap
CFC’s June 2026 policy update has affirmative AI coverage for model hallucinations, AI-generated content, and model drift. Beazley’s September 17, 2026 endorsement adds affirmative wording to its cyber and tech E&O policies. The distinction between those descriptions is important. Beazley describes its endorsement as clarifying AI-related risks already covered within existing cyber cover, rather than explicitly naming the same three perils. Neither description alone establishes protection for bodily injury from autonomous hardware.
Chaucer’s Vanguard AI product, launched in February 2026 and underwritten at Lloyd’s, combines cyber and tech E&O coverage with standalone AI liability. Its predefined allocation rules assign mixed-cause events across cyber, technology failure, and AI behavior. That structure addresses friction between different coverage categories. The product’s defined scope still governs whether a particular physical deployment fits.
A hallucination causing financial loss, a sensor failure causing injury, and an autonomous system executing a bad command present different triggers for coverage. The purchased wording needs to cover the company’s likely failure mode and resulting harm. For larger hardware exposures, the relevant structure is standalone AI liability triggered by AI behavior. Finding that fit requires a carrier experienced in autonomous systems, rather than assuming a modified Tech E&O form will suffice.
Why the underwriting submission is now an AI governance audit — and what that means for coverage outcomes
Access to affirmative coverage depends on evidence about how the company governs its AI. Underwriters writing this coverage require an inventory of tools, models, and agents, written acceptable-use policies, and red-teaming documentation. They also seek governance frameworks such as NIST AI RMF or ISO 42001, agentic AI oversight controls, and third-party vendor contracts. Post-deployment monitoring logs and AI incident response plans complete the picture.
The distinction is between documented controls and unsupported assurances. Companies that can show risk registers, output verification processes, and human oversight protocols have a better chance of getting affirmative coverage. Companies without that evidence can face absolute exclusions at renewal without an alternative offer. Finding an interested carrier does not remove the need to show how the risk is controlled.
If a robot’s recovery behavior is opaque or its failure modes are undocumented, the uncertainty can appear as a higher premium, narrower coverage, or a declination. A generic application built for a conventional business will not adequately describe the models, oversight, and failure modes that determine physical AI coverage. The submission must expose those features if the underwriter is to assess them.
How to determine which gap a specific company faces and where to close it
Analyze what the system does when it fails and who suffers the loss. For software-only tools such as chatbots, recommendation engines, and decision support, the principal exposure is financial reliance on an incorrect output. For those tools, the review needs to check Tech E&O’s affirmative AI wording and any limits carried over from legacy forms. A technology description alone is insufficient to establish that match.
Hardware deployments require a different review of the program. For autonomous vehicles, delivery robots, industrial automation, and drones, the review turns to the actual CGL endorsements, particularly CG 35 08 and its application to the system. If the relevant protection has been removed, the next question is whether explicitly written Product Liability or standalone AI liability can replace it. Systems that make decisions controlling physical processes demand special attention to mixed claims. One incident can combine an allegation of algorithmic failure with bodily injury or property damage, requiring the coverage allocation to be addressed when placing insurance.
Read the endorsement schedule before renewal to check whether last year’s protection continues. Identical operations can receive different AI wording because they renew with different carriers. Governance records serve a second purpose here. The documentation assembled for underwriting also supports a filed claim and provides a contemporaneous record if coverage is disputed.
A specialist broker connects that diagnostic work to placement by reading the policies before binding and approaching carriers that explicitly underwrite autonomous systems. That work is funded through commissions already embedded in the premium. Its value lies in matching a defined failure mode to a defined promise of coverage. For physical AI, that promise must cover the injury or damage the machine can cause as well as name the intelligence that directs it.